

Oportun: Savings & Loans
by oportun
3.9
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.9
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
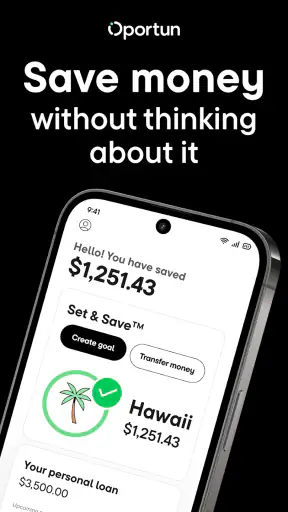
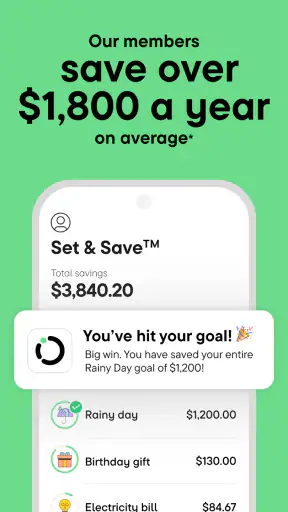
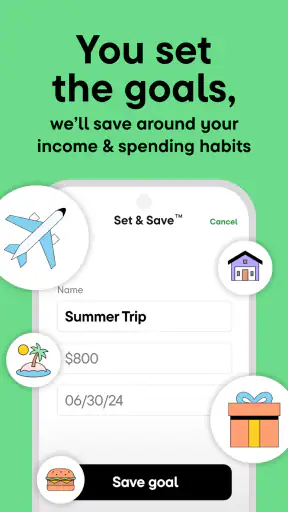
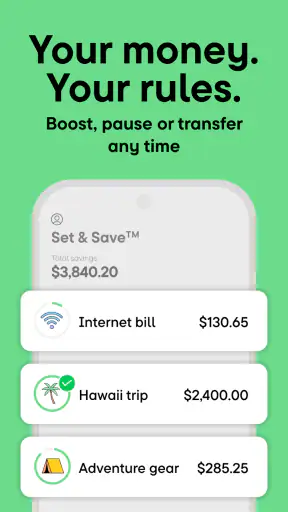
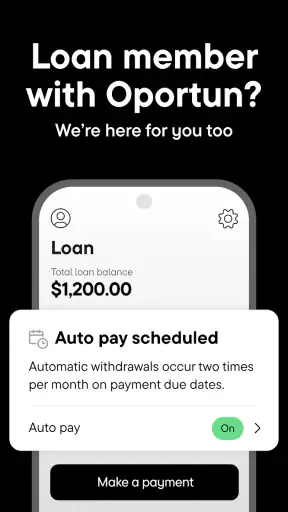
 Analysis by Getfullapps
I approached Oportun as a finance app for people who want saving and borrowing tools in one place, but I paid particular attention to how comfortably it can be used in different everyday situations. Money apps are not only judged by interest, loan options, or account controls. Clear reading, calm navigation, and the ability to finish a task when you are tired, distracted, or using a smaller screen matter just as much.
Oportun is free, developed by oportun, and listed for Everyone. It has grown into a familiar choice in mobile finance, with over one million installs and a 3.9 average from around forty-eight thousand ratings. That combination suggests a useful but not universally smooth experience: many people find value in it, while the rating also leaves room for practical frustrations. After spending time with the app, my view is that it makes the most sense for users who want a guided savings experience and may also be considering personal borrowing, rather than for someone looking for a full traditional bank replacement.
How Oportun feels to read, navigate, and use
I found Oportun easiest to assess when I treated readability as part of the financial decision, not just a design preference. In this section, I look at how its focused mobile flows can help a person stay with one task at a time, and where short screens still call for a slower, more deliberate check. That distinction matters most when a quick glance turns into an actual money decision.
Readability that favors short decisions
The strongest part of Oportun’s design is its focus on individual financial actions. Saving money, checking progress, or exploring borrowing should not require moving through a complicated desktop-style dashboard, and the app generally feels built around those smaller decisions. I found that approach easier to follow than a banking app that puts checking, cards, transfers, investments, alerts, and support into one crowded home screen.
That simplicity can be especially helpful if financial terminology makes you hesitate. A guided flow gives you a clearer sense of what to do next than a blank budgeting spreadsheet. Someone starting a savings habit may appreciate seeing the task as a sequence rather than having to design an entire system from scratch. I would still read every explanation and confirmation carefully, particularly when a screen concerns a loan, repayment, or an automated money movement.
The app’s finance category creates an important expectation: information should be understandable before it becomes actionable. I would not treat a prominent button as a substitute for reading the surrounding details. In borrowing screens, look for the total cost, repayment schedule, eligibility conditions, and any relevant notices before continuing. A clean layout can reduce visual stress, but it should never encourage a rushed financial decision.
Navigation for people with different levels of confidence
Oportun is more approachable than a finance tool that assumes you already know the difference between every account type or lending term. That makes it a reasonable starting point for someone who has avoided savings apps because they seemed too technical. The experience is also likely to suit users who prefer one clear goal at a time instead of a long list of financial controls.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
My practical advice is to move slowly during the first setup. Keep your bank or card information nearby, use a quiet moment, and avoid beginning when you are about to leave home. The most accessible interface in the world becomes difficult when a user is interrupted halfway through identity, account, or money-related steps. If you need to stop, note where you were and review the next screen rather than tapping through simply to finish.
There is a trade-off here. A guided experience can make the first visit less intimidating, but it may feel restrictive to experienced users who want direct control. If you already manage several accounts, use detailed budgeting categories, or need advanced financial reporting, Oportun may feel narrower than a conventional banking app or a dedicated budgeting service. Its value is more focused: it tries to make saving and borrowing understandable on a phone.
Text, contrast, and the limits of a small screen
Financial information deserves more than a quick glance. On a phone, totals, dates, repayment figures, and explanatory text can compete for attention, especially when the display is set to a larger text size or the user relies on screen magnification. I recommend reviewing important figures in a stable position, increasing the device’s text size if needed, and rotating to a larger screen only when that genuinely improves comprehension.
This is one area where expectations should stay realistic. A mobile finance interface may look clean at its default size but become less comfortable when system text is enlarged. Buttons can feel crowded, lines can wrap awkwardly, and a user may need more scrolling before reaching the confirmation controls. I would test the app with the text and display settings you actually use, not with the phone’s factory settings.
For readers who rely on spoken output, the key question is not simply whether text appears on screen. The order in which labels, amounts, warnings, and buttons are presented matters. I would listen through a complete savings or account-review path before trusting the app for a high-consequence action. If a figure is read without enough context, pause and verify it visually or through another official channel.
Motor and sensory considerations
Money tasks can be stressful for users with tremors, limited dexterity, fatigue, or difficulty making precise taps. Oportun is most comfortable when used with deliberate, single actions rather than rapid tapping. I would avoid trying to complete a loan-related form while walking or holding the phone awkwardly. Set the device down, use the hand position that gives you the most control, and check each confirmation before moving forward.
That advice may sound ordinary, but it changes the risk profile of a finance app. A missed tap in a music app is minor; a misunderstood confirmation involving money is not. The app’s guided nature can help by keeping attention on one task, yet it does not remove the need for careful review. Users who depend on switch access, voice control, or alternative input should test the complete journey before relying on it for recurring financial activity.
Visual fatigue is another realistic concern. Someone managing finances late at night, dealing with a migraine, or using a dim screen may find dense financial text harder to parse than expected. I prefer to use Oportun during daylight or in a well-lit room, with the phone’s brightness and display settings adjusted for comfort. A larger tablet or computer may be better for comparing several figures at once, even if the phone remains convenient for quick checks.
For users with hearing loss, the app’s core value should not depend on audio alone, but any support interaction or spoken guidance still deserves attention. Keep written confirmations and records where possible. If an important instruction is delivered in a format you cannot comfortably access, ask for an alternative before making a financial commitment. That is sensible practice with any finance provider, not just this one.
A realistic everyday use case
Imagine someone paid every other week who wants to stop treating savings as whatever remains at the end of the month. They open Oportun after payday, review the planned saving activity, and check whether the amount still fits upcoming bills. The useful habit is not merely turning on a saving feature and forgetting it. It is creating a short review routine: confirm the balance, consider rent and utilities, and make sure the next withdrawal or transfer will not create avoidable pressure.
This workflow is particularly helpful for people who find manual transfers easy to postpone. A dedicated savings experience can add structure without requiring a full budgeting system. However, I would not use an automated approach blindly when income changes from week to week. Freelancers, seasonal workers, and anyone with irregular deposits should review the timing and amount more often, because a plan that feels comfortable after one paycheck may be unsuitable after the next.
Situational access: when the phone is not ideal
Oportun is naturally convenient when you need a quick look at savings progress while away from a desk. That convenience has limits. A cracked screen, poor lighting, weak connectivity, low battery, or a crowded commute can turn a simple task into an error-prone one. I would postpone anything involving a new financial commitment until I could concentrate and see the full screen clearly.
Travel and shared spaces create another layer of concern. Reviewing a balance in public may expose more information than you intend, while entering personal details with someone looking over your shoulder is uncomfortable and risky. The app’s mobile format makes it available in more places, but availability is not the same as privacy. Use a private setting for setup, loan exploration, and support conversations.
People who share devices or have limited personal phone access should think carefully about whether a mobile-first finance routine fits their circumstances. A shared handset can create confusion over sessions, notifications, or saved sign-in details. I would only use the app on a device I control and keep the operating system’s security protections active. This is especially important because the app deals with personal financial information, not just general education.
What it offers compared with usual alternatives
Compared with a traditional bank app, Oportun feels more purpose-built around saving and borrowing rather than serving as a complete everyday account hub. That focus can be an advantage for a beginner who wants less clutter. A bank app may be better for someone who needs deposits, bill payment, account transfers, card management, and a broad transaction history in one established place.
Compared with a spreadsheet, Oportun removes much of the manual work and gives the process a more guided shape. A spreadsheet remains better for users who want total control over categories, custom formulas, irregular income, and long-term comparisons. Compared with a basic savings account, the app may feel more engaging because it puts the saving goal in a mobile workflow, but users should still compare account terms and borrowing costs rather than choosing based on convenience alone.
Its dual focus also deserves caution. Saving and borrowing are very different decisions. A person may download the app for a savings habit and later encounter lending options at a moment of financial stress. I would keep those decisions separate: first decide whether the saving tools suit your routine, then evaluate any lending offer on its own terms. Do not assume that an app that feels easy to navigate is automatically the cheapest or best source of credit for your situation.
Practical friction and remaining barriers
The biggest barrier is not necessarily visual design; it is the seriousness of the subject matter. A friendly mobile flow can make money management feel less intimidating, but it cannot make an unsuitable loan suitable. Users with limited financial literacy may need to look up terms independently or ask a trusted adviser before accepting anything. The app can support a decision, but it should not replace understanding.
Another limitation is that accessibility depends on the whole phone environment. Display scaling, screen-reader behavior, keyboard settings, network quality, and device age can all affect the experience. I would not promise that every path will feel equally comfortable on every handset. Someone who needs highly specialized accessibility controls should test the exact device setup early and keep a non-mobile way to review important financial information.
There is also a cognitive barrier for people who become anxious when numbers change or when an automated action is difficult to interpret. In that case, a manual savings account with a familiar bank may be more reassuring, even if it requires more effort. Oportun is a better fit when guidance reduces hesitation; it is a weaker fit when automation or lending prompts increase uncertainty.
Support and recovery moments deserve the same care as the main interface. If you lose access to your phone, change a bank relationship, or notice an unexpected transaction, you need a clear plan rather than relying on memory. Keep relevant account records in a secure place and review notifications promptly. These habits are not glamorous, but they make a mobile finance service safer and more usable for people with different levels of confidence and ability.
Who should try it, and who should choose something else
I would recommend giving Oportun a serious look if you want a focused savings app, prefer guided steps, and are comfortable reviewing financial details on a phone. It can be useful for a person building consistency, someone who wants saving and borrowing tools from the same developer, or a user who finds a traditional banking dashboard overwhelming.
I would be more cautious if you need a complete everyday bank replacement, detailed household budgeting, complex investment tracking, or a highly customized accessibility setup. It is also not the right choice simply because borrowing appears convenient. Compare the full cost, repayment obligations, and alternatives before making that decision. A credit union, existing bank, or nonprofit financial counselor may be a better route depending on your circumstances.
The app is free, and its current version is 4.177.0 for devices running Android 8.0 or later. It has been available since September 7, 2016, and the store highlights recognition from Bankrate in 2025 and Forbes Advisor in 2024. Those details make it easy to understand why the app attracts attention, but recognition should be treated as a starting point for evaluation rather than a reason to skip the terms.
My inclusive verdict
After looking at Oportun through the lens of different abilities and real-life contexts, I see a product with a useful central idea: reduce the intimidation of saving by giving the user a focused mobile path. Its clearest strength is approachability. Its main weakness is that an approachable interface cannot solve every accessibility issue, financial misunderstanding, or situational problem.
My recommendation is to use Oportun deliberately, not passively. Set it up when you can concentrate, enlarge text if that helps, test the complete flow with your preferred input method, and review every money-related confirmation. Treat savings automation as something to monitor, especially when income or bills change. Treat lending as a separate decision that deserves comparison.
For the right user, it can be a practical bridge between good intentions and a repeatable savings habit. For someone who needs a full bank, advanced budgeting control, or guaranteed comfort with specialized assistive technology, another option may serve better. That balanced position is why I consider Oportun worth trying for focused savings, while stopping short of calling it the universal finance app.
Pros
- Simple savings tools help users build financial habits.
- Loan applications can be managed directly from the mobile app.
- Payment reminders make it easier to track upcoming due dates.
- Account information and transaction details are easy to review.
- Useful option for borrowers seeking alternatives to traditional banks.
Cons
- Loan availability and terms depend on eligibility and location.
- Interest and fees may make borrowing expensive over time.
- Some features may require identity and income verification.
- Savings returns may be limited compared with dedicated savings accounts.
- Customer support response times may vary during busy periods.
FAQs for Oportun: Savings & Loans
What is Oportun: Savings & Loans?
Oportun is a financial app designed to help eligible users manage money, build savings, and access personal loan products through a mobile device. Depending on your location and eligibility, the app may provide tools for setting savings goals, monitoring account activity, reviewing repayment details, and making payments. Available features, rates, and services can vary, so check the current terms before applying.
Can I apply for an Oportun personal loan through the app?
In many cases, eligible users can begin or manage a personal loan application through Oportun’s app or website. Approval is not guaranteed, and the company may review information such as identity, income, banking details, credit history, and other eligibility criteria. Before accepting an offer, carefully review the annual percentage rate, fees, payment schedule, total repayment amount, and any applicable state-specific terms.
Does using Oportun affect my credit score?
Oportun may use different types of credit checks depending on the product and stage of the application. A preliminary inquiry may not affect your score, while a full application could result in a hard credit inquiry. If you receive a loan and make payments, account activity may be reported to credit bureaus, which can help or hurt your credit depending on your payment history. Review the app’s disclosures for current details.
Is Oportun: Savings & Loans safe to use?
The app includes standard financial-app protections, such as account authentication and encrypted data transmission, but users should still take precautions. Download it only from the official Google Play Store or Apple App Store, use a strong and unique password, enable available security features, and avoid sharing verification codes. Never assume a message or phone call is genuine; contact Oportun through official support channels if something seems suspicious.
Are there fees or requirements I should know about before downloading?
Downloading the app is generally separate from the cost of using its financial products. Depending on the service, you may encounter interest charges, origination or late fees, transfer-related costs, or other terms disclosed during enrollment. Requirements can include age, residency, identity verification, a qualifying bank account, income information, and approval criteria. Read the agreement and privacy policy carefully before providing personal or financial information.

Oportun: Savings & Loans
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@digit.co, visit https://digit.co, or review their https://digit.co/about/legal/privacy-policy.










